Surgery Prescribed for the Debt Money Disease: Fighting for the NEED Act

By Nick Egnatz.

Introduction.

The author is a former small businessman who has spent the last decade as an activist for peace and social justice. About five years ago he discovered that our monetary system is not what the people had been led to believe it is. More specifically:

1. The Federal Reserve System is not a part of our government, all 12 Regional Federal Reserve Banks are entirely owned by the same private banks in their districts that they were chartered to regulate. [source]

2. Almost all of what we use for money is created out of thin air by banks when they make loans. The only money created by the federal government are the coins in our pockets and our children’s piggy banks. [source]

3. While the U.S. Department of Engraving prints the Federal Reserve Notes which we commonly refer to as dollar bills of various denominations, the Federal Reserve pays the treasury only for the cost of printing them, about 5 cents for a one dollar bill and 12 cents for a one hundred dollar bill. [source]

“When a bank makes a loan it simply adds to the borrowers’ deposit account in the bank by the amount of the loan. The money is not taken from anyone else’s deposit; it was not previously paid in to the bank by anyone. It’s new money, created by the bank for the use of the borrower.”
Robert B. Andersen, Secretary of Treasury under President Dwight D. Eisenhower [source]

What I concluded was that the basic unfairness of allowing private banks to have the Money Power is at odds with democracy. It certainly flies in the face of our Declaration of Independence’s statement that “all men are created equal”. Perhaps if the people in our country were experiencing prosperity, we could in some crazy way justify giving the Money Power to private banks. After all, Aristotle looked to see what worked and what didn’t work. He junked the latter and supported the former. No doubt, he wouldn’t support our current monetary system. Our country is supposedly recovering from the Global Financial Crisis, but the recovery certainly doesn’t seem to trickle down to the poor or working class. Those who use the term middle class freely admit that it continues to shrink. The basic unfairness and the horrendous results of our monetary system is why I became a monetary reformer and a passionate advocate of the only comprehensive monetary reform bill placed into our Congress — the NEED Act.

I have written several other articles supporting monetary reform and the NEED Act. It has always been my intention to write an article that anyone can understand because economists have their own language and I for one had difficulty following their reasoning. This is not meant to denigrate economists, but those academics seeking a more technical explanation are encouraged to read the NEED Act and other papers included in the references, with particular encouragement in reading German economic sociologist Joseph Huber’s “Sovereign Money in Critical Context“.

While encouraging academics to read Huber, I caution those uninitiated in economist-speak to at the very least read this article first. Huber’s sovereign money, also called new currency theory, is entirely supportive of the NEED Act, but reading and understanding his paper will be a tough slog for those outside the economics community. Indeed, the grasp of his argument will be a challenge for bankers and economists alike. Not because they are unfamiliar with the language, but because they are unfamiliar with even considering reforming the present monetary system.

Money

Money is the very lifeblood of a nation. If a nation’s money system is healthy, society and people will prosper. From a sick or diseased money system, just as the night must follow the day, all manner of ills will follow.

A healthy monetary system is one in which the money is created and issued by the national government, debt-free, and spent into existence for the needs of the nation and its people as determined by its elected, representative government, in amounts that are neither inflationary nor deflationary.

A sick or diseased monetary system is one in which the money is created by banks and loaned into existence, as debt, for those endeavors that are determined profitable for bankers, with little or no regard for the actual needs of the nation and its people.

The Lost Science of Money, Director of the American Monetary Institute Stephen Zarlenga’s tour de force book on money, examines over 3,000 years of monetary history and uses Aristotle’s sage guidance in diagnosing and prescribing the cure for the critically diseased monetary system. It is available at the AMI website monetary.org. A much shorter treatment of the subject, Linking Social Justice to Monetary Reform, is available free online at alpheus.org.

Our understanding begins with Aristotle’s statement “Money exists not by nature, but by law.” The “money by nature” Aristotle referred to was a money as a commodity monetary system in which money was gold, silver or some other commodity, the system of choice for the wealthy who held the gold and silver. Money as a commodity, rejected by Aristotle, embraced by the rich, is the foundation for the debt money monetary system of today. Early goldsmiths or bankers began to issue paper notes for gold or silver given to them for safekeeping. They soon realized that people preferred the paper notes, which were accepted as money within their community by merchants, for their convenience. Very few people turned their paper notes in for their gold on deposit. This led the banker/goldsmiths to issue more, roughly 10 times the amount, paper notes than gold on deposit. Called “fractional reserve lending” it is the philosophical justification for the present debt money monetary system. (Federal Reserve Bank of Chicago 1992 publication “Modern Money Mechanics” available at AMI website, monetary.org)

The author is fully aware that Aristotle died more than 2,500 years ago. He prized justice above all other virtues and there is little doubt that Aristotle, confronted with the basic injustice of the present day debt money system, would prescribe a system of money based on justice or law and the NEED Act (explained below) is that system.

Money: an abstract Power and Duty of the state, that acts as a medium of exchange, for the benefit of the people and society.

 The Debt Money Disease

Our present monetary system is one in which almost all (except the coins) of what is used as money is created by private banks when they make loans.  As the loans are repaid the money is extinguished on their books and no longer exists.  The problem is exacerbated because no money is created with the loan to pay the interest that we most certainly are required to pay.  (Putting aside for now the matter of justice: why should we be made to pay interest to a bank for the use of money that they were allowed to create from the ether of the atmosphere?)  Since repaying our loans with the banks erases the money, it is necessary for us to be in debt so that the system has money with which to function.  Expanding the supply of money can only come from an expansion of the level of debt with which we and our government are burdened.  This system requires us, individually and collectively through our governments, to be in debt at unsustainable levels.  This debt money monetary system (known as fractional reserve banking) is a cancer that must be removed.  


Of course there are apologists for the debt money system, using terms like stocks and flows, who will be quick to point out that there does not have to be enough money in the system to repay all the debts, because this has never been done. We would add, of course it has never been done because any significant repayment of the overall level of indebtedness would result in a crash of the system. The system is designed to keep us in debt, not to allow us to repay our debt. The system is designed for debt slavery, not freedom from debt.

A few symptoms of the debt money disease:

1. The nations of the world are $57 trillion in debt (Economist World Debt Clock)

2. Federal, state and local government debt: $66,000/person (USGovernmentDebt.us)

3. U.S. citizens’ personal debt: $53,000/person (USDebtClock.org)

4. Greece is but the first nation to be destroyed by the disease.

5. Estimated 9 million American families lost their homes to foreclosure (Cornell University)

6. Real U.S. unemployment rate: 23% (ShadowStats.com)

7. Increasing wars and militarism, financed by loans at interest from bankers.

8. Destruction of our environment, since the bankers can realize little profit in its care and nurturing.

9. Inability of U.S. society to fund education, $1.3 trillion student loan debt and broke local school districts.

10. Inability of U.S. society to provide comprehensive healthcare for all.

11. Yet the banking cartel responsible for the debt money epidemic has only one prescription for the people — austerity in increasing doses.

“The mistake lies in fearing money and trusting debt.”
Henry Simons, University of Chicago Economist and advocate of the Chicago Plan that inspired the NEED Act
Economic Policy for a Free Society, 1948, page 199.

The NEED Act Is the Cure

Building upon Aristotle’s empirical conclusion that money is a function of the law; and seconded by the U.S. Constitution (“Congress shall have Power To…coin Money, regulate the Value thereof…”, Article I, Section 8); the complete cure was developed by the American Monetary Institute as the American Monetary Act and put into legislative form before the U.S. Congress in 2011 by Congressman Dennis Kucinich, co-sponsored by Congressman John Conyers, as the NEED Act (National Emergency Employment Defense Act).

The 3 Necessary Reforms of the NEED Act are actually just common sense and represent what most citizens mistakenly think is actually how our monetary system works.

1. Federal Reserve System is nationalized and placed under the Department of Treasury.

2. Bank creation of money as debt, commonly called fractional reserve lending, is decisively ended. Banks will only lend money that already exists.

3. Money is created and spent, debt-free, in non inflation/deflationary amounts for the needs of the nation and its people, immediately putting 10 million people to work, at good paying jobs, by financing the rebuilding of our country’s broken infrastructure.

The NEED Act also calls for specifically funding education, healthcare and addressing the mortgage crisis.

Regarding infrastructure; the NEED Act was written using the American Society of Civil Engineers 2009 Infrastructure Report Card calling for $2.2 trillion in infrastructure repairs. The 2013 Report Card now calls for $3.6 trillion to be spent by 2020 to bring 16 categories of U.S. infrastructure up to a state of good repair. That increases the jobs that would be created from 7 to 10 million, the vast majority of which would be good-paying union jobs that would also each support 6 or 7 other jobs in local economies across the country.(source, source, source).

It is important to note that “Since 1996, the Society (ASCE) has formally recognized civil engineers’ obligation to practice sustainability by making it part of its Code of Ethics.”

“The banks got bailed out, we got sold out.” A chant that echoed throughout Occupy camps across the country. The NEED Act addresses this inequity with a people’s bail-out, called a Citizen’s Dividend, that could and should be $10,000 for every citizen. It is necessary to immediately inject money in the economy when the NEED Act begins, to avoid deflation and a deepening of the present depression. The Citizen’s Dividend instantly does so and begins to ameliorate the disastrous effects of the depression on the people. It will also provide our small businesses with what they need — you and I to have money in our pockets to purchase their goods and services.

The NEED Act stipulates that 25% of all newly created money will be given to the states on a per capita basis to use as they individually see fit for their very real funding needs. And interest free funding will be available to help local governments fund capital expenditures on schools, libraries, sewers, roads and other major projects.

While a transition to clean, renewable energy and other environmental concerns are not spelled out in the NEED Act, it provides the vehicle to fund these with the approval of Congress. All Congress will need is for a knowledgeable citizenry to make its desires clear.

The NEED Act pays off the national debt as it comes due and does so with no inflation. No one from either political party has a plan to do this. They go into crisis mode with regularity trying to agree on increasing the debt ceiling, closing government programs or the government itself. Aristotle understood that a debt money system is incapable of co-existing with a free independent people and a government free of debt.

Before the NEED Act was written, Dr. Kaoru Yamaguchi put the American Monetary Act into his advanced system dynamic computer model and concluded that the national debt can be paid off as it comes due and the ASCE infrastructure repairs (at the time $2.2 trillion, now $3.6 trillion, putting 7-10 million people to work), can be done without causing any inflation. (source)

In 2012, Jaromir Benes and Michael Kumhof, Deputy Director of the Modeling Division at the International Monetary Fund, published the IMF Working Paper “The Chicago Plan Revisited”, in which they concluded the 1939 Chicago Plan, which is the template of the NEED Act, would solve most of the problems of the current Depression.

“At the height of the Great Depression a number of leading U.S. economists advanced a proposal for monetary reform that became known as the Chicago Plan. It envisaged the separation of the monetary and credit functions of the banking system, by requiring 100% reserve backing for deposits. Irving Fisher (1936) claimed the following advantages for this plan: (1) Much better control of a major source of business cycle fluctuations, sudden increases and contractions of bank credit and of the supply of bank-created money. (2) Complete elimination of bank runs. (3) Dramatic reduction of the (net) public debt. (4) Dramatic reduction of private debt, as money creation no longer requires simultaneous debt creation. We study these claims by embedding a comprehensive and carefully calibrated model of the banking system in a DSGE model of the U.S. economy. We find support for all four of Fisher’s claims. Furthermore, output gains approach 10 percent, and steady state inflation can drop to zero without posing problems for the conduct of monetary policy.”

Endorse the NEED Act

The American Monetary Institute welcomes vigorous debate on monetary reform, but is somewhat perplexed by organizations and individuals that claim to work for monetary reform, while ignoring the NEED Act and the AMI.

The NEED Act is the only comprehensive monetary reform ever put forth into our Congress in ready-to-go legislative form. This was a tremendous step and as such it deserves the attention of everyone interested in monetary reform. Evading it while at the same time pushing another monetary reform agenda is similar to an environmental group that concentrates on a single issue such as fracking, Arctic drilling, or the Keystone pipeline, that would completely ignore taking a position on legislation that has been presented to Congress that provides a complete seamless transition to clean sustainable energy. You can’t claim to be a reputable environmental advocacy group and ignore proposed comprehensive environmental legislation like it doesn’t exist. The same can be said for monetary reform legislation.

Those groups that claim to want monetary reform should either publicly endorse the NEED Act or present a paper telling the nation their reasons for not supporting the only comprehensive reform ever put into the U.S. Congress that decisively ends the debt money system and provides a seamless overnight transition to a democratic money system.

It is easy to understand people being led astray by alleged monetary reform groups who think that peaceful coexistence is possible with the debt money system. Once the monstrous nature of the this system becomes known, unsuspecting individuals start looking for a cure for the debt disease. In their search they may be introduced to a group that purports to greatly empathize with their concern over the debt disease and then seemingly innocently prescribes a remedy that leaves the basic debt disease intact, while the patient is treated with the distraction of a traveling medicine show, complete with snake oil elixir that does nothing to strike at the heart of the disease.

The NEED Act diagnoses the debt money system as a cancer that can only be treated by removal. Allowing the disease to continue consigns the country and its people to a future of overwhelming debt, unable to pump the lifeblood of money into the projects most needed — good-paying jobs, clean sustainable energy, 21st century infrastructure, national healthcare for all, education for our youth, etc.

Before entrusting your health and the health of those dear to you to a monetary reform group, ask them if they heartily endorse the only comprehensive monetary reform ever placed before Congress — the NEED Act? If not, tell them you are interested in 21st Century medicine and not snake oil, while running, not walking, to the nearest door. Then join AMI at monetary.org and become part of the monetary reform solution.

Endorsements of the NEED Act should not be limited to monetary reformers. All organizations, unions, political parties, social justice groups, citizen and neighborhood groups, etc. who are interested in a sane, democratic monetary policy are invited to publicly endorse the NEED Act.

Is It Necessary to Enact all 3 Reforms of the NEED Act?

A resounding yes! Historically partial reforms have been tried before and the Money Power has always been able to overturn the partial reforms and get back to the business of amassing wealth at the top by putting us and our governments in greater and greater debt.

The 3 Necessary Reforms of the NEED Act

1. Nationalize the Federal Reserve.
2. Decisively end all bank creation of money.
3. Federal government will create and spend into existence, debt-free, US Money for the needs of the nation and its people.

All 3 Reforms must be done or the Money Power will remain with the banks.

The Bank of England was nationalized in 1946 (Reform #1). But because bank creation of money was not stopped (Reform #2), private banks now still create 97% of the UK’s money.

Presidents Jackson and Van Buren revoked the Second Bank of the U.S.’s charter, effectively ending most bank created money at the time (Reform #2). Misunderstanding the true nature of money, they failed to create and spend debt-free money into existence (Reform #3), bringing on the terrible Panic of 1837.

Debt-free Greenbacks (Reform #3) were created under Lincoln to fight the Civil War and save the nation. Because bank creation of money (Reform #2) was not decisively stopped, the bankers eventually got the upper hand and quashed the Greenbacks.

NEED Act Brings Sanity and Safety to Monetary System

Surgery for a cancer that is destroying its host is standard medical practice. The NEED Act does the surgery and brings our monetary system in line with the Constitution and what people think it should be. The NEED Act is not radical. The only thing radical is to keep the debt money system in place and to continue allowing the Money Power to reside with the bankers and not the people through our elected government.

The NEED Act provides the safe, seamless transition to a just money system that Aristotle would be proud of. Bankers have no need to fear the system. Their liquidity and income should both improve. The people have nothing to fear from the system. Under the present debt money system our money deposited in banks is not ours, but is owed to us by the banks. Under the new system, it will belong to us and be kept in a bank “safekeeping” account. This again, is what most of us mistakenly think is the presently being done.

“How the NEED Act gives an Immediate, Seamless and Non-Disruptive Overnight Transition from a Crisis-Prone Bank Debt System to a Stable Government Money System” by Jamie Walton gives an easy to understand explanation (source).

Moving the NEED Act Forward

Not a single member of the U.S. Congress or Senate has stepped forward to re-introduce the NEED Act. Kucinich is no longer in Congress and Conyers has not done so on his own.

A July, 2014 poll of 100 UK Members of Parliament by Dods Monitoring revealed that 70% mistakenly believed that money was created by the government and only 10% understood that it was created by banks making loans.

Without a reputable scientific poll of U.S. Congress Members on money creation, we must judge their knowledge by their actions. Since none of them now publicly support returning the Money Power to Congress, where the Constitution places it, we must conclude that they too are ignorant on the subject.  The personal experience of colleagues talking with bankers on the subject also brings out their confusion and ignorance.  Many bankers erroneously believing that they lend bank reserves instead of creating the money from thin air.   

It is not hard to understand why our legislators, bankers and the American public are misinformed and confused on the subject of money. Lord Adair Turner is one of the world’s most respected members of the monetary establishment, a member of UK’s Financial Policy Committee, former chairman of Financial Services Authority, Pensions Commission and Committee on Climate Change. He made the following admission in his 2013 featured lecture to the Stockholm School of Economics:

“Modern textbook assumptions. I think it’s fair to say that they make 3 assumptions which are dramatic and wrong over the best simplifications. They tend to assume that what banks do is take deposits from household depositors and lend it to borrowers. That misses the insight that banks create credit and money and purchasing power. They tend still and I have read back through several economic textbooks over the last several months to check this. They tend to say that what banks do with that money is that they lend it to businesses in order to fund those projects that have a higher return than the interest rate. That ignores almost entirely the fact that most credit extension is no longer funding business capital projects.” (source, source)

In other words, our economic textbooks have been lying to us. These concepts are not difficult to understand, we have just been lied to and misinformed by the monetary establishment for years. Those with the most formal monetary education have been duped the most. In that light, it is not difficult to understand why many of our leaders are clueless. Our job is to educate them.

If most legislators are ignorant and bankers confused, it is not difficult to understand the lack of support in Congress for the NEED Act. What our legislators will not be confused about is an aroused citizenry demanding the justice of the NEED Act. This is a matter of education. Every person we talk with, give a pamphlet or book to, every letter to the editor, every comment we make online, every article we post on Face Book, every email, phone call or meeting with our Congressman, every time we speak up at a union meeting or town board meeting, every time we invite a knowledgeable speaker from the AMI to speak: all adds up to a more informed public. As this people’s movement grows it will reach a critical mass and Congress will take notice.

Our own monetary donations to those fighting for the comprehensive reforms of the NEED Act are also vital to the cause.  Those of us that can afford to contribute monetarily to the cause should and those that are unable to can find other ways to support the movement.  

An August, 2015 Gallup Poll shows only a 14% approval rating for Congress and a whopping 82% disapproval rating. To be fair, it is because they have been given an impossible job: “promote the general welfare” of the people and the nation with a cancerous monetary system. An aroused citizenry will have the immediate attention of a Congress with these dismal ratings. People do want their Congress Members, Senators and President to work together to solve the issues and crises that confront us. The NEED Act is not a partisan bill. It was written as non-partisan legislation by the Congressional Legislative Counsel. It’s appeal is universal.

A couple hours of reading Aristotle last night left me completely comfortable that he prized justice above all other virtues.  Of course he couldn’t have prescribed the NEED Act, because he never could have imagined the degree of injustice that flows from the present debt money system. But would he prescribe the NEED Act if he were here today?  Most definitely!

Aristotle has given us insight on money, but it is our struggle now. It is a fight for our destiny. Join us. What shall it be? A free independent people? Or a nation of debt slaves?

Nick Egnatz

Nick Egnatz is a Vietnam veteran. He has been actively protesting our government’s crimes of empire in both person and print for some years now and was named “Citizen of the Year” for Northwest Indiana in 2006 for his peace activism by the National Association of Social Workers. For the last few years he has passionately fought for monetary reform.

Contact Nick OccupyNick@yahoo.com

Reference Materials

Fisher, Irving. 1935. 100 per cent Money. Works Vol. 11, ed. and introduced by William J. Barber, London: Pickering & Chatto, 1997.

Fisher, Irving. 1936.  “100% Money and the Public Debt”. Economic Forum, Spring Number (April-June 1936): 406-420.

Huber, Joseph. 2014a. “Modern Money Theory and New Currency Theory”. Real-world economics review 66, (13 Jan 2014): 38-57.

Huber, Joseph. 2014b. “Sovereign Money in Critical Context: Responding to criticism of monetary reform from a variety of economic viewpoints“. Sovereign Money Website, Oct 2014.

Huber, Joseph & Robertson, James. 2000. Creating New Money: A Monetary Reform for the Information Age. London: New Economics Foundation.

Kumhof, Michael & Benes, Jaromir. 2012. “The Chicago Plan Revisited.” IMF Working Papers 12/202, International Monetary Fund.

Lainà, Patrizio. 2015. “Proposals for Full-Reserve Banking: A Historical Survey from David Ricardo to Martin Wolf”. Economic Thought, Vol 4, No 2 (28 Sep 2015): 1-19.

McLeay, Michael & Radia, Amar & Thomas, Ryland. 2014. “Money in the modern economy: an introduction”. Bank of England Monetary Analysis Directorate. Bank of England Quarterly Bulletin 2014 Q1.

Werner, Richard A. 2012. “How to Turn Banks into Financial Intermediaries and Restore Money Creation and Allocation Powers to the State”. University of Southampton, Centre for Banking, Finance and Sustainable Development, Policy Discussion Paper, No. 3-12 (8 Nov 2012): 2-9.

Werner, Richard A. 2014a. “Can banks individually create money out of nothing? The theories and the empirical evidence”. International Review of Financial Analysis, 36 (2014): 1–19.

Werner, Richard A. 2014b. “How do banks create money, and why can other firms not do the same? An explanation for the coexistence of lending and deposit-taking”. International Review of Financial Analysis, 36 (2014): 71–77.

Yamaguchi, Kaoru. 2010. “On the Liquidation of Government Debt under A Debtfree Money System: Modeling the American Monetary Act”. In Proceedings of the 28th International Conference of the System Dynamics Society, Seoul, Korea, 2010. The System Dynamics Society.

Yamaguchi, Kaoru. 2011. “Workings of a Public Money System of Open Macroeconomies: Modeling the American Monetary Act Completed”. In Proceedings of the 29th International Conference of the System Dynamics Society, Washington D.C., USA, 2011. The System Dynamics Society.

Yamaguchi, Kaoru. 2012. “On the Monetary and Financial Stability under A Public Money System (Revised): Modeling the American Monetary Act Simplified”. Paper presented at the 8th Annual AMI Monetary Reform Conference in Chicago, USA, Sept. 20 – 23, 2012. It was originally presented at the 30th International Conference of the System Dynamics Society, St. Gallen, Switzerland, July 22 – 26, 2012.

Zarlenga, Stephen. 2005. “Moving Monetary Reform to the ‘Front Burner’”. American Review of Political Economy, Vol 3, No. 1 (March 2005): 39-84.

Zarlenga, Stephen. 2002. The Lost Science of Money: The Mythology of Money – The Story of Power. Valatie, NY: American Monetary Institute.
The NEED Act Erases Big Steel’s Claimed Need for Worker Concessions

What do infrastructure repair and a looming steel strike have in common?

The American Society of Civil Engineers 2013 Infrastructure Report Card says $3.6 trillion needs to be spent by 2020 to bring our infrastructure up to modern standards. Congress has been quite clear that it will neither increase taxes or borrowing to accomplish this.

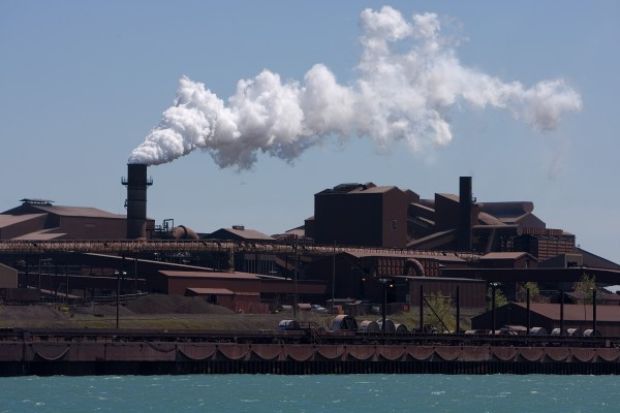
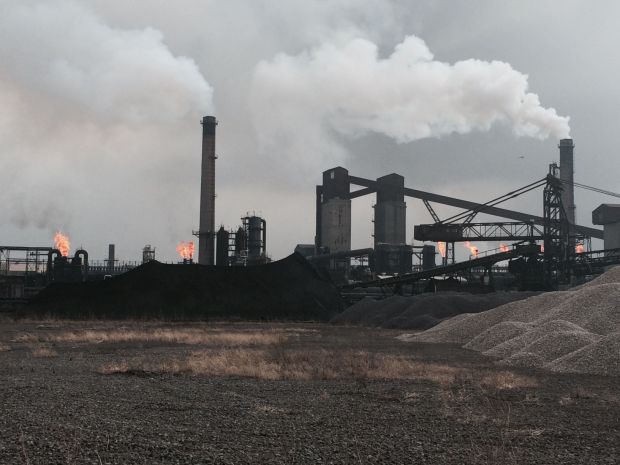
Fixing our infrastructure would put 10 million Americans to work at good-paying jobs and increase our global economic competitiveness.  It requires steel, thus negating management’s argument that demand is down and concessions are necessary.

SteelIndustry2

Management and labor, in both steel and construction industries, should support the only proposal that would fund the repairs.  The NEED Act is comprehensive monetary reform legislation that creates 10 million new, good-paying jobs by fully funding the Infrastructure Report Card, all without increasing taxes or borrowing.  Congress Members of both political parties should be lining up to support the bill, instead they can’t even fix the potholes.

Incredibly, management, labor and Congress have almost all, universally ignored the NEED Act.  Ignored the only proposed legislation that not only puts 10 million Americans to work and rebuilds our nation’s infrastructure, but also provides a bail-out for the poor, working class, small businesses and beleaguered state and local governments.

The NEED Act (National Emergency Employment Defense Act) was put before Congress in 2011 by Congressman Dennis Kucinich and co-sponsor John Conyers.

The 3 Necessary Monetary Reforms of the NEED Act:

1. Makes the Federal Reserve System part of our government, exactly what most people mistakenly believe it is now.

2. Decisively ends all bank creation of money as debt.  Banks will only loan money that already exists, exactly what most citizens mistakenly believe they do now.

3. Our federal government creates and spends new US Money for the needs of the nation and its people, as determined by Congress, in non inflation/deflationary amounts.

Acclaimed Economics Professor Karou Yamaguchi put the reforms that became the NEED Act into his advanced system dynamics computer model and concluded that the ASCE infrastructure modernization could be done, while simultaneously paying off the federal debt, without any inflation.  “Workings of a Public Money System of Open Macroeconomics — Modeling the American Monetary Act Completed”

Former head of the Modeling Division of the International Monetary Fund Dr. Michael Kumhoff and Dr. Jamomir Benes reached the same basic conclusion in their IMF Working Paper “The Chicago Plan Revisited”.

The recovery within the present system from the Financial Crash of 2008 has given us a real unemployment rate of 23% (ShadowStats.com),  the replacement of 2 million high and mid paying jobs with 2 million low paying jobs (National Employment Law Project) and 91-95% of all income gains going to the richest 1% (Emanuel Saez, “Evolution of Top Incomes in U.S.“).  The debt money monetary system responds to the crisis by helping the wealthiest.  Only the NEED Act helps the American people.

SteelIndustry1

Elected government representatives, union leaders and corporate decision makers should all educate themselves on monetary reform and the NEED Act before workers are locked out or a strike is called.  The American Monetary Institute’s 11th Annual Conference on Monetary Reform in Chicago, Sept 10-13, 2015 (monetary.org) is the perfect place for management, labor and government to come together.  All are invited to attend and learn how monetary reform can pay for jobs, infrastructure,  education and healthcare.

Nick Egnatz

occupynick@yahoo.com

References

“USW says it won’t strike yet as contract expiration nears“. Karren Caffarini, Chicago Tribune. Aug 28, 2015.

The NEED Act (National Emergency Employment Defense Act)

American Monetary Institute

American Society of Civil Engineers 2013 Infrastructure Report Card

The original NEED Act referenced the 2009 Infrastructure Report Card and would have created 7.2 million new jobs.  The 2013 ASCE Report Card calls for additional repairs and money and thus would create 10 million jobs. FACT SHEET: Congressman Kucinich’s Jobs Bill to Secure America’s Financial Sovereignty: The Debt Stops Here

Karou Yamaguchi “Workings of a Public Money System of Open Macroeconomics — Modeling the American Monetary Act Completed”

Jaromir Benes & Michael Kumhof, IMF Working Paper “The Chicago Plan Revisited”

John Williams, Shadow Government Statistics

The National Employment Law Project, “The Low Wage Recovery”

Emanuel Saez, “The Evolution of Top Incomes in the United States [2012]” and for 2013.

Linking Social Justice to Monetary Reform

By Nick Egnatz.

PDF version; Spanish translation in anthology; Portuguese translation at AMI.

Social Justice is the struggle to make society work for the vast majority of people. The comprehensive monetary reform of the NEED Act is the necessary first step on the path to realization of this struggle. The following ten points are the major social issues in which I will try to link social justice with monetary reform.

1) How do we end war, militarism and empire?

The primary cause of war, militarism and empire is the profit that these enterprises bring to a relative handful of people. It begins by allowing banks to create our money supply out of thin air when they make loans and then charge us interest for the privilege. Bankers are absolutely delighted to create and loan our government money for militarism, war and empire. It enriches bankers and creates a mutual bond between the banks and government to do whatever is necessary to keep each other in power. True monetary reform contained in the NEED Act decisively ends bank creation of money.

2) How do we transition to clean renewable energy?

Allowing banks to create our money means that they determine what it is created for. The banker’s preference has been and always will be to create money for war, speculation and bubbles, since this has historically given them huge profits. The NEED Act puts the power to create money, debt-free, with our elected government. We the citizens then have the power to insist that our legislative representatives use these funds to make the transition to clean, sustainable energy. Of course, making our representatives more responsive to the people will not be an easy task. But without monetary reform, it is an impossible task.

3) How do we create millions of good paying jobs?

The NEED Act specifically calls upon our government to completely rebuild our country’s crumbling infrastructure, referencing the American Society of Civil Engineers Infrastructure Report Card.[1] The 2013 ASCE Report Card calls for $3.6 trillion to be spent doing so by the year 2020. In addition to bringing our infrastructure into the 21st Century, this creates 10 million new, good-paying jobs. [2]

4) How do we insure that all Americans are paid a wage that allows them life’s basic necessities without putting employers out of business?

No one wants to see businesses close and further reading makes clear the NEED Act’s commitment to supporting small businesses. Yet there is something functionally wrong in a society that facilitates the massive accumulation of wealth at the top while those at the bottom and middle are increasingly unable to simply get by. A simple fix possible under the NEED Act would be to increase the minimum wage to a livable minimum wage ($15). For those employers whose financial and tax statements document that they are unable to pay the new livable wage, the federal government would use newly created US Money to make up the difference until such time as they were able to pay the wage without federal help. An exception could be made for teen age workers whose earnings are not contributing to a family’s livelihood, by paying them a percentage of the living wage and increasing it each year.

5) How do we immediately provide “bail out” assistance to the American people who have been overwhelmed by the recession/depression now in its sixth year?

In 2008, when Wall Street financial markets crashed as a result of the creation of exotic, fraudulent, financial instruments by banks and other institutions, these same banks and financial institutions were rewarded with a $750 billion public bailout and another secret $16 trillion of Federal Reserve loans at zero or close to zero percent interest. All this done while they were functionally bankrupt.[3] The NEED Act will provide a bailout or Citizen’s Dividend to each and every American citizen that could easily be $10,000 for each and every one of us, thus allowing the American people, devastated by bank creation of money as debt, to begin to repair their financial health.

6) How can we best help embattled small businesses grow and thrive?

Bailing out the people with the Citizen’s Dividend immediately gives our small businesses what they desperately need. What they certainly do not need are more loans which they can’t afford . They need you and I to have money in our pockets for the goods and services they provide. The NEED Act gives them this with the Citizen’s Dividend and massive job creation in infrastructure.

Whosoever controls the volume of money in any country
is absolute master of all industry and commerce,
and when you realize that the entire system is very easily controlled,
one way or another, by a few powerful men at the top,
you will not have to be told how
periods of inflation and depression originate

James Garfield, U.S. President 1881, Congressman from Ohio

7) How do we solve the crisis of young Americans entering an abysmal job market, while owing $1.2 trillion in student loan debt? Is it society’s responsibility to educate its youth?

The NEED Act provides society with the vehicle to pay for implementing this principle. One of the reforms of the NEED Act is the incorporation of the Federal Reserve System into our government. It presently is wholly owned by the nation’s private banks, while retaining some ambiguous claimed autonomy from them with a Board of Governors appointed by the President. When the Federal Reserve System is federalized under the NEED Act, its funds will belong to the people and should be distributed to them. A $10,000 Citizen’s Dividend paid to each and every citizen, plus the entirety of the student loan debt could be paid from these funds.[4]

8) How do we pay for an all inclusive national healthcare system?

The NEED Act again provides the vehicle to fund a universal healthcare program that is all inclusive and leaves no one behind. The U.S. is the only major industrial country that does not have such a system. Total U.S. healthcare spending is roughly twice that of those nations that do have a true universal system. The Commonwealth Fund uses national, World Health Organization (WHO) and Organization for Economic Cooperation and Development (OECD) statistics and surveys to rank the healthcare systems of eleven industrial nations. The U.S. ranks dead last overall and dead last in the following categories: cost related access, efficiency, equity and healthy lives. Even in overall quality of care the U.S. ranks only fifth.[5]

9) How can we make our society more democratic?

The NEED Act democratizes our money and makes it the tool of the people and not the banks. As our people become free from debt, they will naturally gravitate toward more democratic political involvement in order to protect this new level of freedom for themselves, their children and grandchildren.

10) How do we pay off our debt, federal and personal?

Under the present monetary system there is no way forward to pay off the federal debt. Under the NEED Act it will be paid off with new US Money as it comes due. The Citizen’s Dividend, 10 million new good-paying jobs, resolution of the student loan crisis and ending bank created money as debt will allow our people to get out of personal debt and become financially healthy.

Debt

The NEED Act specifically calls for the implementation of the ASCE Report Card on Infrastructure; the payment of Citizen’s Dividend in an undetermined amount; directing 25% of all newly created US Money debt-free, to the beleaguered state governments; and providing interest free financing to local governments for schools, sewers, roads, libraries etc. It more generally references spending money for healthcare, education, stabilizing the Social Security retirement system and promoting the general welfare. It will be up to us the U.S. citizens to make the demands upon our elected representatives to use our money for these and other important social programs that will transform our country to the American Dream, rather than the American Nightmare it has become for so many.

Our present monetary system of bank created debt money is unable to provide any relief in the above listed areas. Those at the top of the bank created debt money food-chain will scream that rebuilding our country, putting people to work, providing healthcare, etc will create inflation. Please read the entire article before allowing yourself to be influenced by their self-serving propaganda.
While Pope Francis has probably not closely studied monetary history, his grasp of the structural causes of inequality make him a natural ally of the comprehensive reforms of the NEED Act.

“As long as the problems of the poor are not radically resolved by rejecting the absolute autonomy of markets and financial speculation and by attacking the structural causes of inequality, no solution will be found for the world’s problems or, for that matter, to any problems.” [6] His Holiness Pope Francis of the Catholic Church

Do banks really create money out of thin air when they make loans?

Yes and no. Please, allow me to explain. At the American Monetary Institute’s 10th Annual Conference on Monetary Reform in Chicago this October a discussion began on whether or not banks actually created money when making loans. Monetary reformers will say yes they do and bankers and economists will say no they don’t. Both statements will be somewhat truthful. The monetary reformer’s statement that banks create money is technically incorrect, but actually offers a more correct picture of reality than the banker’s claim that they don’t create money which is technically true, but meant to obfuscate reality.

At the AMI conference Stephen Zarlenga, Director of the AMI, then played Alexander the Great who solved the mystery of the Gordian Knot with a statement striking at the core of the issue.

“Banks do not create money, they create what we use as money when they make loans.” [7]

What we use for money is not real money, although we call it money. Almost the entirety of what is used for money in the U.S. is debt money created by banks when loans are made and then extinguished into the ether of the atmosphere when the loan is paid, except for the interest which goes into the pocket of the banks. The bank simply makes two accounting entries, a credit and a debit balancing each other, the loan check is issued and the money is created from thin air. As the loan is paid off the accounts are reduced and with the final payment the money is extinguished.

Don’t blindly accept my word on this though. Instead, let’s listen to what the Bank of England recently said on money creation. Yes, the Bank of England (BoE), founded in 1694, the UK’s central bank and the model upon which most central banks have been built, including the U.S. Federal Reserve System.

In its first 2014 Quarterly Bulletin the BoE published the revealing and important article “Money Creation in the Modern Economy”, which ” … explains how the majority of money in the modern economy is created by commercial banks making loans…”.

The article explicitly stated the following:

” …Whenever a bank makes a loan, it simultaneously creates a matching deposit in the borrower’s bank account, thereby creating new money.

The reality of how money is created today differs from the description found in some economics textbooks:

Rather than banks receiving deposits when households save and then lending them out, bank lending creates deposits.” [8] (Emphasis Bank of England).

Though usually obfuscated, this understanding of bank credit is not new, as the following quote by Robert B. Andersen, Secretary of Treasury under President Dwight D. Eisenhower, makes clear:

“When a bank makes a loan it simply adds to the borrowers’ deposit account in the bank by the amount of the loan. The money is not taken from anyone else’s deposit; it was not previously paid in to the bank by anyone. It’s new money, created by the bank for the use of the borrower.” [9]

Only the principal amount of the loan is created though, while there is no money creation for the interest that we must pay. As this interest multiplies over the years there is simply not enough money in the system to pay both the principal amounts of the loans that were made and the interest that was not created with the loans. Indeed, no one individual can get out of debt within this system, without someone else, somewhere, going into debt. What? Yes the original debtor can only repay his loan using the debt money in the system that he obtains as wages or in some other manner. For this money to exist it must be created by someone else, somewhere, taking out a loan and going into debt. Is there any question why we are such an indebted society at all levels — individual, federal, state and local?

Thus our national circulating medium
is now at the mercy of loan transactions of banks,

which lend, not money, but promises
to supply money  they do not possess

Irving Fisher
Yale University Economist
Supporter of the Chicago Plan

Bankers and economists will argue that allowing banks to create credit/debt money allows our economy to function and expand in good times and that stopping the practice would bring our economy to a grinding halt.

To answer this argument, we could just observe the sorry results of bank money creation as debt. But first let’s listen to what a leading member of the financial aristocracy has to say on the subject. These remarks were not given in casual conversation over a pint at the local pub, but in a formal address to the prestigious Stockholm School of Economics.

Jonathan Adair Turner is a British businessman, academic, a member of the UK’s Financial Policy Committee, and was Chairman of the Financial Services Authority until its abolition in March 2013. He is the former Chairman of the Pensions Commission and the Committee on Climate Change. He has described himself in a BBC Hardtalk interview with Stephen Sackur as a ‘technocrat’.

Turner’s lecture which was presented to The Stockholm School of Economics via video in September, 2013 is titled “Credit, Money and Leverage: What Wicksell, Hayek and Fisher Knew and Modern Macroeconomics Forgot”. He made some remarkable observations:

7:00 “The flip side of creating purchasing power with credit and money creation is that you create a set of ongoing debt contracts thereafter.”

8:35 “Investment funding has become a small part of what the bank or shadow bank system does.”

14:00 “I think it is reasonable to say that both in undergraduate textbooks today and in advanced economics and in central bank orthodoxy we have tended to work on a way of thinking about the credit creation process which is simply not true.”

14:30 “Modern textbook assumptions. I think it’s fair to say that they make 3 assumptions which are dramatic and wrong over the best simplifications. They tend to assume that what banks do is take deposits from household depositors and lend it to borrowers. That misses the insight that banks create credit and money and purchasing power. They tend still and I have read back through several economic textbooks over the last several months to check this. They tend to say that what banks do with that money is that they lend it to businesses in order to fund those projects that have a higher return than the interest rate. That ignores almost entirely the fact that most credit extension is no longer funding business capital projects.” [10] [11]

If bank credit is no longer funding capital projects in the real economy, what is it funding? One doesn’t have to be a genius or a member of the economic establishment to know that bank credit or money creation is funding wars, bubbles and speculation for the wealthy and debt for the 99%. And let’s not forget Baron Turner’s stark admission that our economic textbooks have been lying to us about the money creation process.

It is correct that simply stopping bank created debt money and not replacing it would bring economic gridlock because as existing loans were paid and no new loans were made the supply of what we use as money would shrivel to almost nothing. But stopping bank creation of debt money and replacing it with US Money, created free and clear of debt and spent into existence for the needs of the nation and its people, would allow our economy and people to flourish. That brings us to legislation that was before the last Congress introduced by Congressman Dennis Kucinich and co-sponsored by John Conyers.

The NEED Act (National Emergency Economic Defense Act) [12]

The NEED Act is a comprehensive monetary reform which was written by the Congressional Legislative Counsel as a non-partisan bill. Its three simple, but necessary, reforms are:

1) The Federal Reserve System is federalized. It becomes part of our government, exactly what most citizens mistakenly think it is now.

2) The banks’ ability to create what we use for money is decisively ended. The banks are not nationalized, but money creation is. In the future when banks make loans, they will be loaning money that already exists, not creating it. Exactly what most citizens mistakenly think they do now.

3) New US Money is created by our federal government and spent, not loaned, into existence, debt-free, for the needs of the nation and its people as determined by our elected, representative Congress. By charter the Monetary Commission, charged with determining how much money to create, will do so in a non inflation/deflationary manner.

Let’s listen to one more expert from the financial establishment in this case Martin Wolf, a British journalist, considered to be one of the world’s most influential writers on economics. He is associate editor and chief economics commentator at the Financial Times. In his April 24, 2014 Column for the Financial Times, titled “Strip Private Banks of Their Power to Create Money”, he wrote:

“Printing counterfeit banknotes is illegal, but creating private money is not. The interdependence between the state and the businesses that can do this is the source of much of the instability of our economies. It could – and should – be terminated.”

Later he recommends The Chicago Plan that The NEED Act was based on.

“A maximum response would be to give the state a monopoly on money creation. One of the most important such proposals was in the Chicago Plan, advanced in the 1930s by, among others, a great economist, Irving Fisher. Its core was the requirement for 100 per cent reserves against deposits. Fisher argued that this would greatly reduce business cycles, end bank runs and drastically reduce public debt. A 2012 study by the International Monetary Fund staff suggests this plan could work well.”  [13] (100% reserves simply means that banks will only loan money that already exists, exactly what the NEED Act calls for.)

While Martin Wolf does not specifically mention The NEED Act, his solution is to strip banks of their money creation power and have the government spend money into circulation. These are reforms two and three of The NEED Act. Reform one, nationalizing the Federal Reserve System or in the case of the UK, the Bank of England, was already done in the UK after WWII.

The IMF study referred to by Martin Wolf was written by Jaromir Benes and Michael Kumhof, “The Chicago Plan Revisited”. I was privileged to hear Dr. Kumhof lecture on the subject at the American Monetary Institute’s Annual Convention 2013 in Chicago. [14]

Debt Money Is the Natural Result of a Money as a Commodity Monetary System

Our present system of debt money created by banks is the result of misinformation disseminated by the wealthy for millennia. It exists because those with power, gold and silver were able to use their influence in determining that money was gold or silver — money as a commodity monetary system. The next step in the middle ages were goldsmiths as early bankers issuing paper receipts for gold stored in their vaults. When the receipts or notes became widely acceptable by other merchants, those whose gold was stored with the goldsmiths were happy with the convenience of the paper notes and generally reluctant to redeem them. The goldsmith/bankers realized this and began to issue paper notes or receipts for about ten times the gold that they actually held in their vaults. Thus was born what became known as fractional reserve lending — the banks/goldsmiths issuing notes for something (gold or silver) that they didn’t actually have.

This is the logic underpinning the present bankers’ creation and control of what should be our money. Except now within the Federal Reserve System there is no longer any fractional reserve, the banks create deposits and money together when we take out loans and use the entire Federal Reserve System to do so.

What invariably happened in these money as a commodity systems was that they became progressively more and more unequal with all the gold and silver either owned by a few rich people or residing in the temples. Ancient Sumerian kings were forced to issue periodic debt jubilees (forgiveness of debt) because society simply became unworkable when almost everyone had become indebted as slaves. The ancient Hebrew society experienced the same results as Sumer and called for such a jubilee every 49 years when all those indebted as slaves would be freed. (Bible, Leviticus 25:8-13)

Money By Law

In stark contrast to money as a commodity monetary systems is money by law. Rome had a money by law monetary system of bronze bars and coins from the reign of King Numa in 716 BC until wars further and further from home resulted in the minting of silver coins to pay their armies in foreign lands beginning around 310 BC. The bronze money by law monetary system was still used exclusively at home until the Punic Wars with Carthage resulted in Rome converting into a silver coin money as a commodity system by about 212 BC. Rome became a world power with its money by law monetary system. Its decline coincided with its changeover to a money as a commodity system.

Before Lycurgus became king of Sparta around 800 BC, he traveled much of the known world to get ideas about how to have the fairest and most equitable system for his future subjects. On the island of Crete he met the poet Thales “the lawgiver” who returned to Sparta to advise him. Lycurgus then eschewed the money as a commodity system of gold and silver and instead installed a money by law monetary system of elongated iron discs. They were called Pelanors because they resembled small cakes of the same name. They intentionally had no value outside the law. They were dipped in vinegar when hot during the smelting process. This made them brittle and useless for anything but money by law. Lycurgus also instituted land reforms, dividing the land more equally among the Spartan citizens.

Sparta grew into a Hellenic power during the almost 400 years of a money by law monetary system. Around 415 BC Sparta became more and more involved in wars far from home and regressed to a gold and silver money as a commodity monetary system. This was done largely as a result of successful foreign conquests and the capture of gold and silver from the vanquished that then made its way back to Sparta. The combination of war and a money as a commodity monetary system was then the cause of Sparta’s demise as a world power. But for 400 years each, both Rome and Sparta grew and prospered as examples to the world of money by law monetary systems.

The philosopher Aristotle decisively came down on the side of money by law when he made his famous statement, “Money exists not by nature (as gold or silver), but by law.” Unlike modern economists that use undecipherable theories to support the present system of bank created money as debt, Aristotle instead relied entirely upon empirical evidence of what worked and what didn’t work. [15]

Our own history shows that money by law worked extremely well.

U.S. Money by Law

Throughout U.S. history one can clearly detect a struggle and search for a fair and equitable system of money. For example, Jefferson and Madison were battling with the private 1st Bank of the United States; Jackson and Van Buren were clashing with the private 2nd Bank of the United States, the Greenback and Progressive Movements, more recently parts of the Occupy Movement. Unfortunately, until now the banking class has had the money, clout and the ability to befuddle the issue enough to retain its money creation privilege. Bank accountants then mystify the explanations of their occult practices, while the 99% are swallowed up in the quicksand of debt and taxation from present and past monetary and fiscal policies.

It is well that the people of the nation
do not understand our banking and monetary system,

for if they did, I believe there would be
a revolution before tomorrow morning

Henry Ford
Founder Ford Motor Company

The justification for giving the Money Power to the private First and Second Banks of the U.S. and the private Federal Reserve System was that they were issuing money as a commodity backed by gold and silver in their vaults. But the reality was that the banks that Jefferson, Madison, Jackson and Van Buren fought, the private banks and their private Federal Reserve System that citizens battle today, have always created our money supply out of thin air by issuing debt money created by banks. This has been done historically by a process called “fractional reserve lending” in which banks loaned out about 10 times the actual money they had in reserve. Recently this process has been advanced to the point that the banks make the loans first and then use the entire Federal Reserve System to borrow whatever funds are necessary to back up the loan.

This is why citizens in the U.S., countries across the globe such as Greece, Cyprus and Spain, our own cities like Detroit and states like Illinois, are all becoming debt slaves to a private banking class. [16]

Let’s look at the successful examples of money by law in our own history.

Colonial Scrip: North American colonists suffered from a lack of money throughout their history. Remember that the colonies were created to benefit the mother country and not to provide a good life for the colonists. English law forbade sending coinage to the colonies and the Dutch also kept coinage from New Amsterdam (New York). Economic activity became so difficult that Massachusetts even made a small amount of Indian wampum legal tender in an effort to create a circulating medium.

Massachusetts rediscovered the science of money in 1690 when she issued “bills of credit”, the first paper money in the West. She spent them into circulation paying for the colonial expenses. Pennsylvania followed in 1723 with paper money that was loaned instead of spent into existence. A much less perfect system, but still effective in alleviating the shortage of money in the colony.

The colonial money by law fiat currencies dramatically improved life in the colonies, facilitated the building of real infrastructure and reversed the flow of emigrants who for decades had been moving back to England. The colonial scrip was successful at alleviating hardship and fostering a new spirit of independence in the colonies, Parliament responded with the Currency Act of 1764, banning the use of colonial paper currency in all private transactions and making the ban retroactive for ten years. “It was the enforcement of this policy that brought on the Revolution” observed the American political economist Alexander Del Mar in his History of Money in America. [17]

Continental Currency: The Continentals helped us to win our independence. The Continental Congress authorized $200 million and issued that amount to finance the new nation’s struggle for independence. Long after they made the Revolution a reality, they have been smeared by pundits as inflation money. What actually happened was that the British counterfeited billions of them and eventually destroyed the Continentals. Yet they still carried us over a 5 1/2 year period of Revolutionary War and to within 6 months of final victory. They gave us our nation!

Greenbacks: $450 million of paper Greenbacks were issued to fight the Civil War, in lieu of paying usurious interest rates to private banks. Eventually they were exchanged dollar for dollar with gold coins, but few were returned as Americans liked their paper money by law Greenbacks. The Greenbacks allowed us to keep the nation that the Continentals had given us and the Colonial Paper Scrip had helped to build. [18]

The National Bank Acts of 1863, also known as the National Currency Act established chartered national banks that could issue bank notes, backed by the U.S. Treasury. The bankers supported the Bank Acts as a means to eventually replace the public Greenbacks and gain full private control of the U.S. monetary system.

Salmon P. Chase, the U.S. Treasury Secretary and U.S. Senator from Ohio who was involved in the passage of the bill, later regretted his involvement. He stated that,

“My agency, in procuring the passage, of the National Bank Act, was the greatest financial mistake of my life. It has built up a monopoly that affects every interest in the country. It should be repealed. But before this can be accomplished, the people will be arrayed on one side and the banks on the other in a contest such as we have never seen in this country.” [19]

Result of a Debt Money Created by Banks Monetary System

The current monetary system doesn’t work for the people. The present system of debt money created by private banks works just fine for the private banks and those that own them. And the numbers are staggering. According to the Global Debt Clock the world is $54 trillion in public debt. [20] And the picture of the aggregate U.S. Debt does not look good either:

Federal debt $ 17.9 trillion $56,000 / each citizen

State gov debt $ 1.2 trillion $ 4,000 / each citizen

Local gov debt $ 1.9 trillion $ 6,000 / each citizen

Consumer debt $11.68 trillion $37,000 / each citizen

Total $103,000 / each citizen*

* Does not include business debt. [21]

U.S. household consumer debt profile:

Average credit card debt: $15,593

Average mortgage debt: $153,184

Average student loan debt: $32,511

* These figures are averages for those who have debt, households with credit card debt, mortgages and students and graduates with student loans. [22]

Almost half of all Americans have zero net worth, as their debts exceed their assets. [23] [24]

These sorry statistics, which increase with each passing day, are the direct result of allowing banks to create and control our money as debt. The conclusion is inescapable, that a debt money monetary system must be decisively ended if we are ever to improve society for the vast majority of people. Because the U.S. is the world’s hegemonic leader, both militarily and economically, monetary reform must come first in the U.S., thus allowing the countries of the world to follow our lead and break the shackles of debt.

The Russian writer and social reformer Leo Tolstoy made the following statement more than a century ago about the debt money system:

“Money is a new form of slavery, and distinguishable from the old simply by the fact that it is impersonal, there is no human relation between master and slave. “ [25]

Federal Reserve System

The 100 year old Federal Reserve System is not a part of our federal government. It belongs to neither the legislative, executive nor the judicial branches of our federal government. It consists of a Board of Governors in Washington, D.C. and twelve regional Federal Reserve Banks (New York, Boston, Philadelphia, Richmond, Cleveland, Chicago, Atlanta, St. Louis, Dallas, Minneapolis, Kansas City, San Francisco). These twelve regional Federal Reserve Banks are wholly owned by the private banks in their respective districts. The Board of Governors calls itself a “federal government agency”. [26]

Over time, whoever controls
the money system, controls the nation

Stephen Zarlenga
Director American Monetary Institute

Yet the sole claim of Federal Reserve accountability to our federal government and the citizens is that the seven member Board of Governors is nominated by the President and confirmed by the Senate to fourteen year terms. The Federal Open Market Committee (FOMC) decides policy and is composed of the seven members of the Board of Governors and five of the twelve regional Federal Reserve Bank presidents who serve one year terms on a rotating basis. The president of the New York Federal Reserve Bank does not rotate and is always a voting member of the FOMC. All twelve Federal Reserve Bank presidents take part in policy discussions and formal meetings that take place eight times per year.

The private banks in the U.S. own the Federal Reserve Banks and the Federal Reserve “Division of Banking Supervision and Regulation is responsible for the oversight of U.S. banking holding companies, foreign banking organizations operating in the U.S., and state-chartered member banks of the Federal Reserve System.” [27]

Thus, the banks in essence regulate themselves.

To complete the circle of villainy we will listen to testimony from Senator Dick Durbin of Illinois in April, 2009 when he told a Chicago radio station,

“And the banks — hard to believe in a time when we’re facing a banking crisis that many of the banks created — are still the most powerful lobby on Capitol Hill. And they frankly own the place.” [28]

Recapping: The private banks create our money out of thin air when they make loans, regulate themselves via the Federal Reserve System that they own, and last, but not least, the private banks own Congress.

The citizen’s only protection in this predatory system is in the membership of the appointed and confirmed Board of Governors. But the Board of Governors and the Fed regional bank presidents that make policy are exclusively members of the financial establishment; either CEOs of huge banking corporations or academic economists who have been thoroughly vetted in supporting the entire criminal enterprise.

The Federal Reserve System does return all profits made, after expenses and stock profits are paid to its private bank owners. But the profits made in the money creation process by the private banks that own the Fed are kept and not returned to the federal government. The best in-depth article on the Fed was written in 2008 by American Monetary Institute Director Stephen Zarlenga, titled “Is the Federal Reserve System a Governmental or a Privately controlled organization?” [29]

The FED normally operates in secret and makes every attempt to befuddle us and keep us in the dark about money. Every now and then they slip up and let just a little truth escape. For example in a 1992 updated publication by the Federal Reserve Bank of Chicago titled “Modern Money Mechanics” it was stated that,

“The actual process of money creation takes place in commercial banks. Banks can build up deposits by increasing loans and investments… This unique attribute of the banking business was discovered several centuries ago… At one time, bankers were merely middlemen. They made a profit by accepting gold and coins for safekeeping and lending them to borrowers. But they soon found that the receipts (bank notes or IOUs) they issued were being used as if they were a means of payment. These receipts were acceptable as if they were money since whoever held them could go to the banker and exchange them for metallic money… Then bankers discovered … that they could make loans merely by giving borrowers their promises to pay (bank notes). In this way banks began to create money… More notes (IOUs) could be issued than the gold and coin on hand, because only a portion of the notes outstanding would be presented for payment at any one time… Demand deposits (checks) are the modern counterpart of bank notes. It was a small step from printing notes to making book entries to the credit of borrowers, which the borrowers in turn, could ‘spend’ by writing checks.” [30]

Barry Goldwater, conservative Senator from Arizona and 1964 Presidential candidate, stated the issue quite simply:

“The financial system has been turned over to the Federal Reserve Board. That Board administers the finance system by authority of a purely profiteering group. The system is Private, conducted for the sole purpose of obtaining the greatest possible profits from the use of other people’s money.” [31]

It took the Federal Reserve System only sixteen years to bring on the Great Depression and completely crash the American economy.

Louis McFadden, Chairman of the House Banking and Currency Committee in 1933, brought Articles of Impeachment against the Federal Reserve Board of Governors, the Officers and Directors of the Federal Reserve Regional Banks and Others for their collusion in causing the Great Depression. He stated the following:

“The Great Depression was not accidental; it was a carefully contrived occurrence… bankers sought to bring about a condition of despair here, so that they might emerge as rulers of us all.”

“We have in this country one of the most corrupt institutions the world has ever known. I refer to the Federal Reserve Board and the Federal Reserve Banks. Some people think the Federal Reserve Banks are U.S. government institutions. They are private credit monopolies; domestic swindlers, rich and predatory money lenders, which prey upon the people of the United States for the benefit of themselves and their foreign customers….The truth is, the Federal Reserve Board has usurped the Government of the United States by the arrogant credit monopoly, which operates the Federal Reserve Board.” [32]

The American Monetary Institute Leads the Way toward Monetary Reform

• In 1991 Stephen Zarlenga, drawing on 35 years of experience in finance, securities, insurance, mutual funds, real estate and futures trading begins focused research on the money problem.

• In 1996 he helps found the American Monetary Institute to further his research.

• He draws on 800 monetary source books and materials to form his thesis encapsulated in his book The Lost Science of Money.

• In 1999 Conzett Verlag of Zurich, Switzerland translates and publishes The Lost Science of Money in German.

• In 2002 Zarlenga refutes Mitchell Innes’ Credit Theory of Money. [33]

• In 2002 The Lost Science of Money is published in English by the American Monetary Institute.

• Zarlenga and the AMI build upon the monetary reform of the “Chicago Plan”, written in the Great Depression by Henry Simons and Paul Douglas of the University of Chicago and vigorously endorsed by Irving Fisher, Yale University; Frank Graham, Charles Whittlesley, Princeton University; Earl Hamilton, Duke University. The Chicago Plan was sent to hundreds of university economists and supported by the vast majority. [34]

The mistake lies
in fearing money
and trusting debt

Henry Simons
University of Chicago

• In 2006 AMI releases the American Monetary Act and presents it in Philadelphia at the Eastern Economic Association Conference for general comment.

• In 2010 Professor Kaoru Yamaguchi, Doshisha University, Kyoto, Japan puts the American Monetary Act through his advanced computer system model and concludes that it will allow the implementation of the American Society of Civil Engineers 2009 Infrastructure Report Card (then $2.2 trillion, in 2013 $3.6 trillion) and simultaneously pay off the federal debt as it comes due and will do so without causing inflation. [35]

• In 2011 Congressman Dennis Kucinich and co-sponsor Congressman John Conyers release the National Emergency Defense Act (NEED Act), based upon the AMI American Monetary Act, into the 112th Congress. For the first time offering the nation comprehensive monetary reform and a workable alternative to bank creation of what we use for money as debt. [36]

• The Yamaguchi study and The Lost Science of Money come to the attention of Michael Kumhof, Deputy Division Chief of the Modeling Division, International Monetary Fund Research Department. He reads The Lost Science of Money and proclaims it “a masterful work”. [37]

• In 2012 Dr. Kumhof and Dr. Jaromir Benes of the IMF release an IMF Working Paper “The Chicago Plan Revisited” which echoes the findings of the Yamaguchi study and the NEED Act. [38]

• Dr. Kumhof is then invited to speak on three occasions to officials at the Bank of England.

• In 2013 Adair Turner lectures the Stockholm School of Economics that “modern textbook assumptions are dramatic and wrong…they tend to assume that what banks do is take deposits from household depositors and lend it to borrowers. That misses the insight that banks create credit and money and purchasing power…That ignores almost entirely that ignores almost entirely the fact that most credit extension is no longer funding business capital projects“. [39]

• In 2014 the Bank of England’s 1st Quarter Bulletin Money Creation in the Modern Economy “explains how the majority of money in the modern economy is created by commercial banks making loans…“. [40]

• In 2014 Martin Wolf’s Financial Times column is entitled “Strip Private Banks of Their Power to Create Money”. [41]

• In 2014 environmental and economic sociologist Joseph Huber of the Martin Luther University, Germany refutes the mistaken monetary reforms of Modern Monetary Theory (MMT) with a paper “Modern Monetary Theory and New Currency Theory”. [42]

• In 2014 the UK Parliament conducted a debate on money creation in which the progressive MPs Michael Meacher and Austin Mitchell promoted the money by law concept and referenced to the Positive Money organization, the sister organization in the UK of the American Monetary Institute. [43]

Building a Nation

The knee jerk reaction from the economics profession will be that the money by law system of the NEED Act, also called sovereign money, will result in inflation. This is the same economics profession that has rubber stamped its approval of the debt money created by banks system over the last century and the massive inequality that it has spawned. A 1913 dollar has lost 96% of its worth in 2014. [44] It is worth just 4% of what it formerly was in 1913 and this inflation has all occurred within the present system of bank created debt money. All accomplished with nary a peep from the economics profession.

The classic historic example of hyper inflation occurred in Germany from 1923-24. On insistence by the Allies the German central bank, the Reichsbank, became in 1922 privately owned, while before and during the war it had been controlled and operated by the German government through appointment of its president and directors by the Emperor. The 1922 edict took away governmental control and made the Reichsbank entirely a private operation. The hyper inflation followed immediately and only stopped when the government brought the central bank back under its control and issued the new Rentenmark. [45] The first reform of the NEED Act brings our Reichsbank, the Federal Reserve System, out of the control of private banks and into the Treasury Department of our federal government.

The money by law Greenbacks of the Civil War era did not cause inflation. Nor did the Continental Currency of the Revolution. The Continentals gave us our nation and were eventually brought down, not by inflation, but by massive British counterfeiting.

Of course there will be concerns about how much money can be created. But the charter of the NEED Act stipulates that the amounts created will be neither inflationary, nor deflationary. Money created for things of actual value to a society has never been inflationary and there is no reason to believe that it will be now. If and when inflation starts to rear its head, the amount of money created will have to be cut back or what the money is being spent for will need to be changed.

The real unemployment rate in the U.S. is in the 23% range, counting those that are no longer jumping through government hoops in looking for work and those who are working part time, but need a full time job. [46] The difference between a full employment economy and the Gross Domestic Product (GDP) of our present economy is called a GDP gap. There is no reason to believe that creating new sovereign, money by law US Money to close this GDP gap would be inflationary as long as the money was used to provide actual value to society.

The NEED Act allows us to create money to insure that our people are paid a living wage; to address the tremendous challenge of global warming and climate change; to insure that all Americans have healthcare without unduly burdening our employers; to educate our youth; to provide a bailout to our citizens that have borne the brunt of the depression; to provide customers with funds for our small businesses; to rebuild our country’s crumbling infrastructure making our country competitive in the global arena; putting 10 million Americans to work a good-paying jobs doing so; and pay off existing student loans and thus allow an entire generation of Americans to escape from crushing debt, marry, have families and partake in the American Dream. These are not the building blocks of inflation, they are the building blocks of a nation.

Author’s Conclusion

It is this author’s conclusion that improved levels of social and economic justice within the capitalist system are possible only through the monetary reform of the NEED Act. Why did the Bank of England, after 320 years in operation, choose now to address the bank creation of money? Why did establishment insiders Adair Turner and Martin Wolf do the same? Why did the UK Parliament on November 20, 2014 have a discussion on money creation for the first time in 170 years? [47] Brought about in large part by the efforts of Positive Money, a UK based monetary reform movement similar to the American Monetary Institute in the U.S. [48]

In either case there is a fundamental realization that a monetary system that produces progressively greater and greater inequality–as the bank money creation as debt system does–is unsustainable and eventually will have to be replaced. Or the elites have realized that people have become more knowledgeable about money creation and want to bring up a discussion. But then ultimately dismiss the real reform of the NEED Act and allow a non reform such as adding state banks to the mix which does nothing to fundamentally change the bank money created as debt monetary system.

I believe that the capitalist class is very interested in self preservation. If necessary to preserve their dominant position in society, the 1% may very well ultimately sacrifice the bank money creation as debt system to remain at the top of the societal heap. This would allow the elites, at least for now, to save the most basic capitalist principle of private ownership of the earth and its resources, without which capitalism could never exist.

It is beyond the scope of this article to challenge this basic assumption of the capitalist system. While this author believes that monetary reforms of the NEED Act are the only way to save the capitalist system, he also believes that the democratization of our money, accomplished by the NEED Act, strengthens the possibility of an eventual socialist system. Neither system though, socialism nor capitalism, will ever be successful for the vast majority of the people as long as bankers control our money creation.

The NEED Act is the keystone that will allow our government to address war, militarism, empire, clean renewable energy, 10 million new jobs, a living minimum wage, small business health, citizens’ financial health, student loan debt, education, real national healthcare, a more democratic society and actually paying off our federal debt. Within the present monetary system of bank created money as debt there are and will be no proposals that can adequately deal with any one of these issues, let alone the entirety of them.

Those who care about these issues have a duty to educate themselves further about monetary reform. Go to the website for the American Monetary Institute. Do your own research. Contact me for assistance. Then work within your organizations, unions and Congressional Offices for formal endorsements of the NEED Act.

Nick Egnatz is a Vietnam veteran. He has been actively protesting our government’s crimes of empire in both person and print for some years now and was named “Citizen of the Year” for Northwest Indiana in 2006 for his peace activism by the National Association of Social Workers.

In 2012 Nick began working closely with the American Monetary Institute in support of the comprehensive monetary reform contained in the NEED Act, as the necessary first step to ending U.S. militarism, wars, empire and the growing inequality between those at the top and the rest of the heap in our society.

Contact Nick at OccupyNick@yahoo.com

Endnotes

1. American Society of Civil Engineers, 2013 Infrastructure Report Card.

2. The original NEED Act referenced the now outdated 2009 ASCE Report Card that would have created 7 million jobs American Monetary Institute. Fact Sheet on Infrastructure Job Numbers.

3. “The Fed’s $16 Trillion Bailouts Under-Reported‘, Forbes, September 20, 2011.

4. Jamie Walton, “The Fed, Student Debt and How to Fund a Student Jubilee“, American Monetary Institute.

6. Information Clearing House, Reuters, “Pope Francis Calls Unfettered Capitalism ‘Tyranny‘”.

7. American Monetary Institute 2013 Conference on Monetary Reform.

8. “Money Creation in the Modern Economy“, Quarterly Bulletin, 2014 Q1, Bank of England.

9. Create Real Democracy, “Monetary History Calendar”.

10. Adair Turner, “Money, Credit and Prices…“, Part 3. You Tube. Emphasis mine (the numerals indicate the time of the quotes in the video).

12. American Monetary Institute, NEED Act, National Emergency Employment Defense Act.

13. Martin Wolf, “Strip Private Banks of Their Power to Create Money“, Financial Times, April 24, 2014.

14. Jaromir Benis & Michael Kumhof, “The Chicago Plan Revisited“, International Monetary Fund Working Paper, .

15. Stephen Zarlenga, The Lost Science of Money, American Monetary Institute, 2002.

16. Nick Egnatz, “Occupying the NEED Act“, American Monetary Institute.

17. Alexander Del Mar, History of Money in America, 1900.

18. Zarlenga, The Lost Science of Money.

19. Create Real Democracy, “Monetary History Calendar”.

20. The Economist, Global Debt Clock.

22. Nerdwallet, “American Household Credit Card Debt Statistics: 2014”. [Updated to: “2019 American Household Credit Card Debt Study“.]

24. Silvia Allegretto, “The State of Working America’s Wealth, 2011“, Economic Policy Institute.

25. Create Real Democracy, “Monetary History Calendar”.

26. Federal Reserve System Online,

27. Board of Governors Federal Reserve System, “Banking Supervision and Regulation“.

28. Glenn Greenwald, “Top Senate Democrat: bankers ‘own’ the U.S. Congress“, Salon.com.

29. Stephen Zarlenga, “Is the Federal Reserve System a Governmental or a Privately controlled organization?“, American Monetary Institute.

30. Federal Reserve Bank of Chicago, 1992, “Modern Money Mechanics”, American Monetary Institute.

31. Create Real Democracy, “Monetary History Calendar”.

32. Create Real Democracy, “Monetary History Calendar”.

33. Stephen Zarlenga, “Critique of Innes’ ‘Credit Theory of Money’“, American Monetary Institute.

34. Paul Douglas, Irving Fisher, Frank D. Graham, Earl J. Hamilton, Willford I. King, Charles R. Whittlesey. “A Program for Monetary Reform”, July, 1939, original document reprinted with handwritten notes by American Monetary Institute.

36. American Monetary Institute, National Emergency Employment Defense Act, NEED Act,

37. Jaromir Benis & Michael Kumhof, “The Chicago Plan Revisited“, IMF Working Papers 12/202, International Monetary Fund, p. 13. 

38. Benis & Kumhof, “The Chicago Plan Revisited”.

39. Adair Turner, “Credit, Money and Leverage: What Whicksell, Hayek and Fisher Knew…”.

40. Bank of England, Quarterly Bulletin, 2014 Q1, “Money Creation in the Modern Economy”.

41. Martin Wolf, “Strip Private Banks of Their Power to Create Money”, Financial Times, April 24, 2014.

45. Benis & Kumhof, “The Chicago Plan Revisited”, p. 16.

46. Alternate Unemployment Charts. ShadowStats.com.

48. Positive Money.

Coda

Major organizations promoting monetary reform:
American Monetary Institute (USA)
Positive Money (UK)
Monetative (Germany)
Ons Geld (Netherlands)

The full list of national organizations can be found at: International Movement for Monetary Reform

Special thanks to Greg Coleridge and the Monetary History Calendar at Create Real Democracy for providing society with a wonderful compilation of monetary quotes. at

The on-line version with all active links and a 16-page pdf printable format can be found at the Alpheus web site of Govert Schuller, the editor of this pamphlet.

© 2014 by Nick Egnatz. Permission to copy and distribute this document is hereby granted provided that this notice is retained on all copies and that copies are not altered.

Bilderberg 2014: A Secretive Elite Wonders if Privacy Exists


Introduction

If you are interested in studying parapolitics–i.e. the practice of attaining political ends through secrecy and covert operations by intelligence agencies, think tanks and private networks (Scott)–there might be no better group to look into as the “Bilderberg”, the annual three-day conference in which the cream of the crop of the Atlantic power elite can freely exchange differing viewpoints and enhance mutual understanding, as they like the public to believe.

This year (2014) the conference was in Copenhagen, in a Marriott hotel guarded by “a double ring of three-metre (10ft) high security fencing” and a little army of security guards. As usual, the hotel was closed off to regular guests and certainly to journalists, two of whom were arrested for asking questions of the organizers at the hotel bar (Skelton).

The conference is conducted under the so-called Chatham House Rule by which “participants are free to use the information received, but neither the identity nor the affiliation of the speaker(s), nor that of any other participant, may be revealed” (Chatham House). Participants can make notes, but are not allowed to take those home. What they can take home is a list of the participants and their contact information. There was no press conference nor a communiqué and participants agreed not to give interviews to the press. As the organizers state about the conference in a press release: “There is no desired outcome, no resolutions are proposed, no votes are taken, and no policy statements are issued”.

The organization does publish a list of participants and mentions the topics of discussion, but is otherwise stingy in providing more information. Its headquarters has the same address as the main address of the University of Leiden in the Netherlands at a picturesque canal just around the corner where I used to live. It might have a staff of just one person. All the footwork and research though seems to be done at the Council on Foreign Relations (CFR) in New York, which many consider the most influential of long-term policy planning organizations in the West. They were the architects of the United Nations, the International Monetary Fund, the World Bank and the then still-born World Trade Organization (Shoup & Minter). Many of the Bilderberg Steering Committee members are prominent members of the CFR.

The Non-Reporting by Reporters

The media were well represented, but do not hold your breath to receive a report or, God forbid, a scoop by John Micklethwait, Editor-in-Chief of The Economist; Natalie Nougayrède, Director and Executive Editor of Le Monde; Martin Wolf, Chief Economics Commentator of The Financial Times; or by any of the other five highly placed journalists present from Austria, Italy, Spain, Sweden and Turkey. The condition of their participation is to put away their notebooks and keep silent afterward.

If Bilderberg is ever mentioned in such media it is to ridicule conspiracy theorists and their inflated, paranoid ideas about who runs the world. Any attempt at critical analysis, of which I deem them perfectly capable, seems verboten, though reporting during the last decade has improved. And small chance to see academic studies mentioned which view such gatherings from a non-conspiratorial social science angle like the work of Ian Richardson, Carol Quigley, Anthony Sutton, Laurence Shoup, Holly Sklar, G. William Domhoff, or Kees van der Pijl. This is unfortunate, because such knowledge is now pushed under and into the dark where it gets mixed with antisemitism, alien agendas and–to which undersigned has contributed–occultism. Fortunately, besides the mainstream The Guardian in the United Kingdom, there are some journalists representing smaller and fringe media reporting on the Bilderberg like Jon Ronson, Jim Tucker, Alex Jones and others with widely differing qualities of reporting.

One of the questions discussed this year in Denmark was “Does privacy exist?” Given the extensive security measures surrounding the conference and the strict rules of engagement inside, this question drips with sinister irony. As Charlie Skelton, reporting on the spot for The Guardian, UK’s foremost paper to tackle under-reported stories, contemplates:

There’s something distinctly chilling about the existence of privacy being debated, in extreme privacy, by people such as the executive chairman of Google, Eric Schmidt, and the board member of Facebook Peter Thiel: exactly the people who know how radically transparent the general public has become.

Now, add to this list of social media representatives Reid Hoffman, the co-founder and executive chairman of LinkedIn, and Clara Shih, CEO and founder of Hearsay Social (about whom more later), and you have a nice group of experts for the elite to consult about social media and privacy.

Maybe the best way to frame the topic is to realize that the elite there gathered in Denmark takes privacy and secrecy for granted as a right for themselves and considers the public’s privacy as merely a privilege to be tinkered with in secrecy. Facebook’s business model requires transparency to shape its members into predictable, profitable consumers and the NSA’s Snowden-blown secret mandate is to monitor the world’s communication patterns and treat ordinary Americans as incipient terrorists. Both NSA and Facebook tinker with their interpretations of privacy and political rights as much as they can get away with.

Little Case Study

To help maximize the reach of “highly regulated companies” like banks and insurers into our social networks to make money, is a California start-up company Hearsay Social. Without a hint of alarm about the company’s 1984-ish agenda The New York Times reported that,

To help bank employees navigate regulations, Hearsay offers software that includes libraries of approved content to post on social media, and it allows employees to customize their messages as long as they are vetted before publication. In addition, the program lets its users “listen” to activity on their social networks (Alden).

I mention this factoid because the CEO of this company, Clara Shih, was also in Copenhagen and might be the youngest Bilderberg attendee I know of. She is 32. Her monitoring software might be in high demand by other very important participants from the banking sector like HSBC’s chairman Douglas Flint and its senior adviser Sherard Cowper-Coles; Paul Achleitner and Josef Ackerman of Deutsche Bank; Franco Bernabe, VP of Rothschild Europe; and representatives of international financial institutions like Christine Lagarde, head of the IMF and Benoît Coeuré, executive board member of the European Central Bank. Add to this list some higher-ups from Lazard and Goldman Sachs and the picture is again of an enormous concentration of power and influence present at this Bilderberg conference.

NATO War Council?

Besides the social media and banking companies, both the intelligence and military community are also well represented at this Bilderberg meeting. Where else would one find–besides a possible NATO war council–professionals with the highest security clearance and military authority like Keith B. Alexander, the former commander of the U.S. Cyber Command and former director of the NSA; Philip M. Breedlove, the Supreme Allied Commander of Europe; the Secretary General of NATO, Anders Fogh Rasmussen; and John Sawers, head of the UK Secret Intelligence Service? Again, a quite impressive grouping.

Because the crisis in the Ukraine is officially on the Bilderberg agenda and NATO can be construed as an instrument of western, corporate finance capitalism (extremely well represented in Copenhagen) which together push into Eastern Europe and beyond to find more living space for corporations to extract wealth, this meeting might indeed be an informal war council to formulate a medium to long term policy which might satisfy all major–and sometimes divergent–corporate, military, intelligence and financial interests involved. After all, the name of the game in these clubs is consensus building around long-term corporate policy preferences (Richardson).

The Facebook-Intelligence Interface

As a last point, one might find in the above mentioned Peter Thiel an interesting interface between social media and the intelligence community as he sits on the board of Facebook and was behind Palantir Technologies, “a secretive data-mining company that made its name working for the CIA” (Waters), whose current CEO Alex Karp’s whereabouts in June was … you guess … also in Copenhagen. Once you look into the biographies of the attendants, very interesting patterns come to the fore and cry out for further investigation.

One might ask Thiel for the sake of transparency what actionable information he privately divulged and received on the question of privacy during the conference. And if the information might impact the running of Facebook. As long as he does not mention with which participants he had an exchange and is not talking to the press, he is not breaking the rules, at least not the ones set by the organizers. Such questions are relevant as Thiel is on the record stating he wants even more and better technology to monitor the world to prevent terrorism (Waters).

Academic Scrutiny

Fortunately a group of social scientists did manage to publish one of the rare academic monographs on Bilderberg, titled Bilderberg People: Elite power and consensus in world affairs. They did interview some of the attandees. Their research program is based on the following legitimate curiosity:

“In order to comprehend the significance of elite transnational networks, we need to gain some degree of transparency on what is taking place within them. We need to understand the interdependencies and motivations of participants, as well as the relationship between power and consensus within such communities. And, crucially, we need to understand how consensus is formed and disseminated within, and beyond, networks of this kind” (Richardson, 36).

Framing the Bilderberg like this might not be exciting, but the imperative to correctly understand these people, rather than demonizing them, is of great importance if attainable, realistic reforms of this world are on your agenda.

One of the pertinent questions in this study is about how to best frame our understanding of this club. One quoted reference about the origin of Bilderberg asked in its title ” CIA plot, socialist conspiracy, or new world order?” (Wilford), to which the authors answered, though tucked away in a footnote, that “Wilford’s research provides extremely qualified support for the new world order hypothesis” (Richardson et al). This hypothesis is basically stating that Bilderberg tries to understand and shape the process of globalization through secretive consensus building within the transatlantic elite. In their conclusion Richardson et al come to the following succinct formulation of their findings:

This book has sought to demonstrate that they are an integral part of a system of world politics that exists beyond any formal conception of constituency or process. They facilitate communication primarily between transnational business interests and internationalist political elites, and their focus, not always conscious, is related to the structural challenges of globalization (217).

Much more could be written about this group, but for now, I hope you have obtained a taste for parapolitics as a relevant discipline to understand a bit better how the world works. It is not an invitation to grand conspiracy theorizing, but a call to vigilance because the cumulative effect of a series of petites conspiracies in the many shapes corruption takes, combined with the secretive long-term policy formation process within the transnational elites, might be equal to the dystopian disasters the grand conspiracy theorists project.

Sources

Alden, William. “Hearsay Social Raises $30 Million to Give Bankers an Online Presence“. The New York Times. Sept 5, 2013. Web.

Bilderberg Meetings. “Participants“. Web (cached).

Bilderberg Meetings. “Press Release“. Web (cached).

Chatham House. “Chatham House Rule“. Web.

Richardson, Ian; Andrew Kakabadse; Nada Kakabadse. Bilderberg People: Elite Power and Consensus in World Affairs. (London & New York; Routledge, 2011). Print.

Skelton, Charlie. “Bilderberg at 60: inside the world’s most secretive conference“. The Guardian. May 29, 2014. Web.

Waters, Richard. “Lunch with the FT: Peter Thiel“. Financial Times . Dec 20, 2013. Web.

Wilford, Hugh. “CIA plot, socialist conspiracy, or new world order? The origins of the Bilderberg group, 1952–55”. Diplomacy & Statecraft 01/2003; 14(3):70-82. Print.

Background

Aubourg, Valerie. “Organizing Atlanticism: the Bilderberg group and the Atlantic Institute, 1952–1963”. Intelligence and National Security, 18:2 (2003), 92-105. Comparing two private, transatlantic organizations which started in the 1950s and flourished in the 1960s.

Domhoff, G. William. The Higher Circles: The Governing Class in America: An Investigation of the Men and Women who govern our Country (New York: Vintage Books, 1969). Penetrating sociological study of the power elite. Special chapter on the CFR and one on conspiricist views of the upper-class.

Domhoff, G. William. The Powers That Be: Processes Of Ruling Class Domination In America (New York: Vintage Books, 1978) Study of the ways and means of power-elite hegemony. Most revealing chapter on the role of the CFR in creating the UN, IMF and Worldbank.

Eringer, Robert. The Global Manipulators: The Bilderberg Group… the Trilateral Commission… covert power groups of the West. Bristol, UK: Pentacle Books, 1980. Print. An early journalistic foray into Bilderberg-land and how the media failed the public. First chapter here.

Estulin, Daniel. The True Story of the Bilderberg Group. Walterville, OR: TrineDay, 2007. Print. “For some 15 years, Estulin has been a thorn in the sides of the Bilderbergers, relentlessly hunting down their secret meeting places, gaining inside sources who divulge what goes on behind closed doors, even photographing attendees and publicly disclosing it all.”

Pijl, Kees van der. The Making of an Atlantic Ruling Class (London: Verso, 1984). Print. Study of the development and integration of the American and West European post-WWII corporate elite.

Quigley, Carroll. The Anglo-American Establishment: From Rhodes to Cliveden (New York: Books in Focus, 1981). Print. Eminent historian reveals historical roots of a secret cabal within the Anglo-American establishment. Study written in 1946 and finally published posthumously in 1981.

Quigely, Carroll. Tragedy and Hope: A History of the World in our Time (New York: Macmillan, 1966). Print. Tucked away in a vast narrative of 1870-1945 world history, eminent historian reveals evidence of the existence of a secret cabal within the Anglo-American establishment and its impact on history.

Richardson, Ian. “Bilderberg, Elite Consensus and the Media“. The Huffington Post, UK Edition. July 13, 2011. Web.

Richardson, Ian; Andrew Kakabadse; Nada Kakabadse. “Shaping Global Political Realities: The Workings of Transnational Elite Networks“. World Financial Review. March-April 2012. Web.

Ronson, Jon. Them: Adventures with Extremists (New York: Simon & Schuster, 2002). Two chapters dedicated to his adventures to find out more about Bilderberg.

Ross Sr., Robert Gaylon. Who’s Who of the Elite: Members of the Bilderbergs, Council on Foreign Relations, Trilateral Commission, and Skull & Bones Society. (N.p.; RIE, 1995). “The book is an excellent “reference” as to specifically who is affiliated with each specific elite organization, as well as cross-referencing what branch of government, industry, etc. their “day-job” corresponds with”. Different editions available.

Scott, Peter Dale. Deep Politics and the Death of JFK. Berkeley and Los Angeles: University of California Press, 1993.

Shoup, Laurence H. and Minter, William. Imperial Brain Trust: The Council on Foreign Relations and United States Foreign Policy (New York: Monthly review Press, 1977). Print. Academic study of the history, network and influence of the CFR, especially its architecture of the post-WW II order with institutes like the UN, IMF and World Bank, and later its 1980s Project laying the groundwork for trilateralism, the G-7 Summits and the Trilateral Commission.

Thompson, Peter. “Bilderberg and the West”. In Trilateralism, Holly Sklar (Editor).

Sklar, Holly (Editor). Trilateralism: The Trilateral Commission and Elite Planning for World Management (Boston: South End Press, 1980). Collection of case studies of the imperialist power of the TC. Includes an annotated TC membership list.

Sutton, Antony and Patrick Wood. Trilaterals Over Washington. 2 vols. (Scottsdale, Arizona: August Corp., 1978, 1981). Groundbreaking study on the Trilateral Commission by academic investigators.

Sutton, Antony. America’s Secret Establishment: An Introduction to the Order of Skull & Bones (Billings, Montana: Liberty House, 1986). After obtaining the membership list of this Yale senior secret society, Sutton could connect the dots from his Wall Street trilogy and lay out the central role S&B played in fomenting wars and revolutions and controlling education.

Wala, Michael. The Council on Foreign Relations and American Foreign Policy in the Early Cold War (Oxford & New York: Berghahn Books, 1994). “Based on extensive analysis of primary sources, this book clearly delineates the Councils activities- its study and discussion groups and its publications – and the developing international political, military, and economic situations.”

Added in 2020:

Ronson, Jon. 2001. “The Bilderberg Group“. Part 5 of “Secret Rulers of the World”. Documentary. World of Wonder Productions, 27 May 2001.

Wisnewski, Gerhard. 2014. The Bilderbergers, Puppet-Masters of Power?: An Investigation into Claims of Conspiracy at the Heart of Politics, Business and the Media. West Hoathly, UK: Clairview Books.

Kantor, Lukas. 2017. “Bilderberg Group and Transnational Capitalist Class: Recent Trends in Global Elite Club as Vindication of neo-Marxism.” Critique, 45/1-2: 183-204.

Gijswijt, Thomas W. 2007. Uniting the West: The Bilderberg Group, the Cold War and European Integration, 1952-1966. PhD. Thesis / Dissertation. Heidelberg University, 2007.

Gijswijt, Thomas W. 2019. Informal Alliance: The Bilderberg Group and Transatlantic Relations During the Cold War, 1952-1968. Oxon, UK & New York: Routledge.

Willimon, Beau, et al. 2013. House of Cards. The Complete Fifth Season.
Bohemian Grove is the inspiration for “Elysian Fields” in season 5.